India’s Latest Urea Tender Signals Relief on Global Fertiliser Costs
12 October 2026, New Delhi: India’s state-run fertiliser importer, Indian Potash Limited, closed a urea import tender on October 7 with offers coming in roughly 10 percent cheaper than the country’s previous purchase in August, a sign that global nitrogen fertiliser costs are continuing to ease heading into the winter cropping season. West coast port offers ranged from $356.25 to $416.50 per tonne, while east coast offers ranged more widely from $352.10 to $465 per tonne, according to figures reported by Briefs Finance and traced to Bloomberg wire reporting. Total offers received were more than double the quantity India had sought, reflecting ample global supply currently chasing India’s business.
The tender itself, issued by IPL on September 23 for 1.7 million tonnes (1 million tonnes for west coast ports and 700,000 tonnes for east coast ports), had been closely watched as a potential benchmark for fourth-quarter global urea pricing, since India is the world’s largest fertiliser importer and other buying countries routinely track its purchase prices.
A volatile year for nitrogen prices
This year’s price swings have been unusually sharp. Fighting earlier in 2026 connected to the wider Iran conflict disrupted critical Middle Eastern gas and fertiliser supply chains, briefly pushing India’s urea import price to as high as $959 per tonne in April, more than double the levels seen later in the year. As the supply squeeze eased and Chinese exporters returned to the market, prices fell steadily, with a June tender settling near $445 to $449 per tonne and an August tender, boosted by heavy Chinese participation, dropping further to roughly $390 to $394 per tonne. By late September, global benchmark prices had begun ticking back up, with Middle East granular urea quoted near $465 per tonne FOB and Brazilian granular urea around $485 per tonne CFR, making October’s lower Indian tender results a modestly reassuring signal rather than a clear-cut trend reversal. India’s own urea imports for the April-to-August period ran about 133 percent higher year on year, at roughly 4.75 million tonnes, even as domestic production rose about 4.4 percent, underlining how dependent the country remains on imports despite capacity additions.
What it means for the season ahead
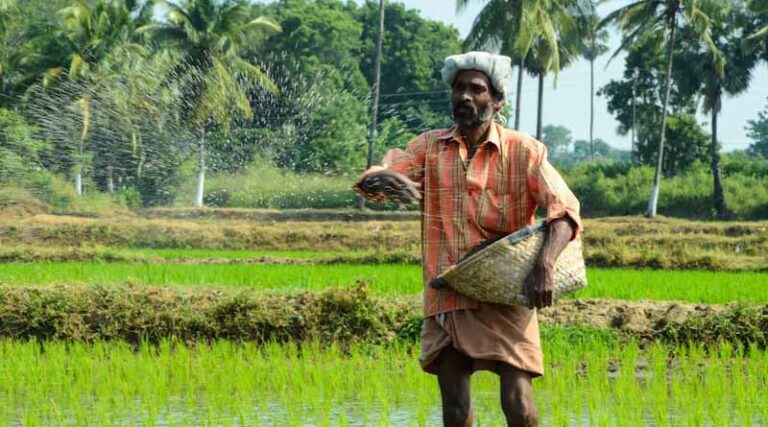
The timing is significant for Indian agriculture. Farmers are now preparing to sow winter crops, including wheat, rapeseed and chickpeas, all of which rely heavily on nitrogen application through urea at the sowing and early growth stages, meaning demand is set to rise through November and December regardless of price trends. Cheaper import costs, if sustained, could ease pressure on the government’s fertiliser subsidy bill, since India sells urea to farmers at a fixed, heavily subsidised price and absorbs the difference between that price and the import or production cost. However, trade sources cautioned that any relief from lower import prices typically takes a full cropping season to filter through to what farmers actually pay, and other input costs, particularly diesel for irrigation and field operations, remain elevated and are offsetting some of the benefit.
A global pricing signal
Because India’s tender results function as an informal global benchmark, the softer October pricing has implications well beyond the subcontinent. Fertiliser majors such as Nutrien, Mosaic and Yara, along with large buyers in Bangladesh, Sri Lanka and Turkey, typically adjust their own pricing expectations in response to how India’s tenders clear. For Latin American growers, particularly in Brazil, where urea demand is tied closely to the second corn crop (safrinha) application window, a continued easing in global nitrogen prices would be a welcome offset to persistently high input costs that have squeezed margins across the region’s row-crop sector for much of the past two seasons. How much of this relief materialises depends heavily on how much low-cost Chinese prilled urea, currently the cheapest major supply source at around $372 per tonne FOB, remains available for export through the rest of the year.
Also Read: Syngenta Launches New Fungicide Kadexa SC in Canada
Global Agriculture is an independent international media platform covering agri-business, policy, technology, and sustainability. For editorial collaborations, thought leadership, and strategic communications, write to pr@global-agriculture.com